Interest-Only Mortgage Calculator: See the Step-Up Before It Surprises You
Use the free Interest-Only Mortgage Calculator to compare your IO payment, the post-IO step-up payment, and total lifetime interest against a standard amortizing loan.
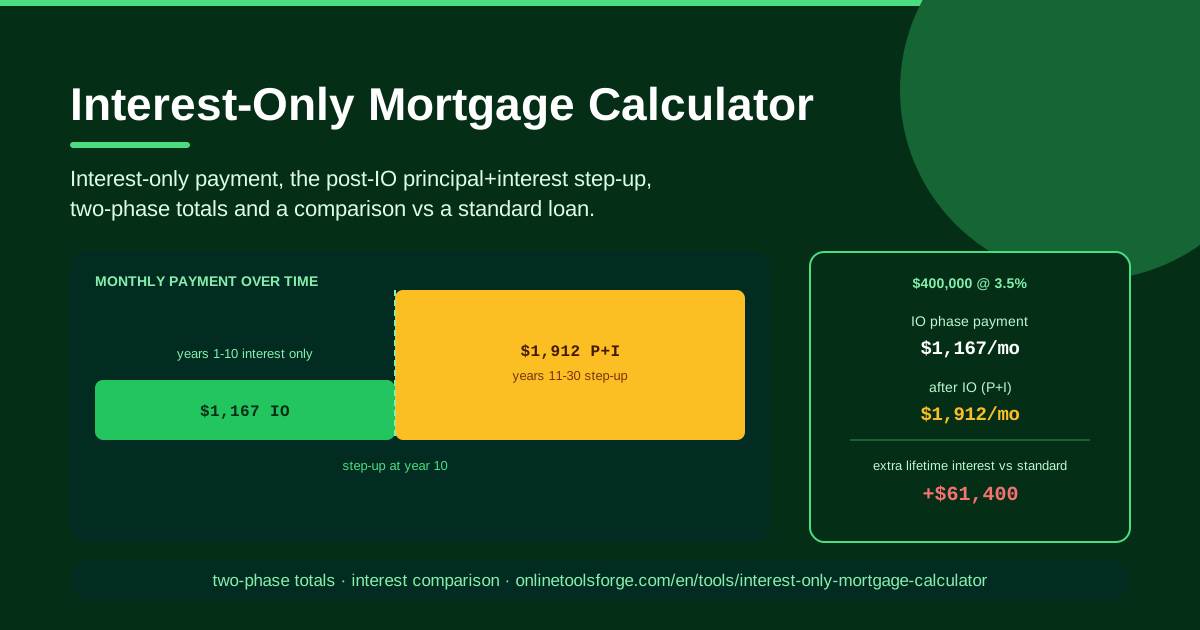
Table of Contents
An interest-only mortgage can feel like a discount: for years your payment covers only interest, far smaller than a standard repayment. The free Interest-Only Mortgage Calculator at Online Tools Forge shows what that arrangement really costs — not just during the IO phase, but across the whole life of the loan.
The trap is what happens when the interest-only period ends. Your payment does not return to normal; it jumps above what a standard loan would have charged from day one, because the full principal must be repaid over a shorter remaining term. This step-up catches many households off guard, years after they signed.
The Interest-Only Mortgage Calculator puts every number on the table before you commit. Enter your loan amount, rate, IO period, and full term, and the tool computes the low IO payment, the higher post-IO principal-and-interest payment, two-phase totals, and an interest comparison against a standard amortizing loan — all client-side, instantly and privately.
Why Use Interest-Only Mortgage Calculator?
- See the step-up before the lender shows it to you. IO marketing leads with the low payment; this tool computes the post-IO payment so you know what you will owe in month 121, not just month 1.
- Quantify the extra lifetime interest. Interest keeps accruing on the untouched balance during IO; the calculator totals both phases and compares them with a standard loan, turning a hidden cost into dollars.
- Model different IO periods in seconds. Five years or ten? Change one input and watch the step-up and totals move immediately.
- Plan around irregular income. Commission earners and investors with lumpy cash flow are IO loans' natural audience; confirm the lower obligation truly fits your cash flow.
- Negotiate with real numbers. Arriving with the step-up amount and interest comparison turns a sales pitch into arithmetic.
- Keep your data private. The calculator runs entirely client-side — nothing is uploaded and no sign-up is required.
Key Features
| Feature | What it does |
|---|---|
| Interest-only phase payment | Monthly IO payment — loan amount times the rate, divided by twelve. |
| Post-IO step-up payment | Payment recomputed over the remaining term after IO ends, showing the monthly jump. |
| Two-phase totals | Payments summed for the IO and repayment phases, separately and combined. |
| Standard loan comparison | Same amount, rate, and term run through a standard amortizing loan, with extra lifetime interest reported. |
| Flexible inputs | Any loan amount, rate, IO period, and full term to match your actual offer. |
| Client-side execution | All math in your browser — instant results, nothing leaves your device. |
Two details stand out:
- The step-up figure is the headline. It determines whether you can afford this loan, yet most borrowers never calculate it before signing.
- The interest comparison makes the trade-off explicit. IO is not automatically bad, but you should know precisely what the flexibility costs in dollars.
How to Use Interest-Only Mortgage Calculator
- Enter the loan amount and interest rate. Use the expected principal and the quoted annual rate; the calculator converts it to a monthly charge automatically.
- Set the interest-only period and the full term. A 10-year IO period inside a 30-year term leaves 20 years for repayment.
- Read the interest-only payment. Your monthly obligation during IO — interest only, no principal reduction.
- Read the post-IO step-up payment. The higher principal-and-interest payment that begins when IO ends; compare it with the IO payment to see the jump.
- Compare total interest. It shows combined interest across both phases and the gap versus a standard amortizing loan — the true price of the IO structure.
The Step-Up Nobody Plans For
During the interest-only phase, your payment is pure interest: balance times the monthly rate. On a $400,000 loan at 6.5 percent, that is roughly $2,167 a month. It feels light because it is — no principal is repaid, and your balance never moves.
When the IO period ends, the lender recalculates the payment to amortize the full $400,000 over only the remaining term. With a 10-year IO inside a 30-year loan, thirty years of repayment get squeezed into twenty. At the same rate the payment jumps to roughly $2,982 — about $815 more, a 38 percent increase and about $454 above a standard 30-year payment from the start.
The IO phase alone burns $260,000 in interest without touching the balance; twenty years of elevated payments then add roughly $315,700. Total interest: about $575,700, versus about $510,200 on a standard 30-year loan — roughly $65,000 more for the identical loan. Some of that premium buys real flexibility; know the number before you buy it.
Who legitimately benefits? Borrowers with irregular income — surgeons paid per procedure, founders awaiting a liquidity event, seasonal business owners — can hold fixed obligations low during IO while directing surplus cash at principal voluntarily. Buyers bridging between homes, or investors selling within the IO window, also qualify. In every case, the plan depends on actually doing what the IO phase enables.
The equity trap is what happens when there is no plan. Pay interest only for ten years and you own the same share of the home as on day one; if prices fall, you can owe more than the property is worth, unable to refinance or sell. The step-up then lands on a household with no equity cushion and no exit.
Practical Use Cases
Comparing IO vs Standard on a $400,000 Loan
Enter $400,000 at 6.5 percent, 10-year IO, 30-year term. The calculator shows an IO payment of $2,167, a standard payment of $2,528, and a post-IO step-up of $2,982. Total interest lands near $575,700 versus about $510,200 for the standard loan — roughly $65,500 more. Can your budget absorb month 121?
Planning Bonus-Based Principal Payments
If you receive an annual bonus, use the IO phase deliberately: pay the low interest-only amount monthly, then attack the principal with a yearly lump sum. It gives the baseline to measure how much each voluntary payment shrinks the eventual step-up.
Investor Cash-Flow Analysis
For a rental, cash flow matters more than principal reduction. If rent covers the $2,167 IO payment but not the $2,982 step-up, you must sell, refinance, or restructure before IO ends — and you can plan that date from day one.
Stress-Testing a Rate Rise
Post-IO payments are rate-sensitive because the repayment window is compressed. If rates rise one point before you refinance, a 20-year amortization at 7.5 percent costs roughly $3,220 — nearly $1,050 above your IO payment. Ask honestly whether your future income covers it.
Best Practices
- Plan the step-up before you sign. If you cannot name the month the payment jumps and to what, you are not ready for an IO loan.
- Pay principal voluntarily during IO. Extra principal payments are the simplest way to neutralize the step-up.
- Run a refinance check 24 months before IO ends. Lenders underwrite on today's income, rates, and equity — give yourself time to qualify.
- Never assume appreciation will save you. Rising prices are a bonus, not a repayment strategy; the calculator assumes your balance never shrinks during IO.
- Match the IO period to a real event. If nothing anchors the end of the IO phase, choose a standard loan.
- Re-run the numbers whenever anything changes. A new rate or a shorter IO period changes everything, and the tool takes seconds.
Ready to see your real numbers? Open the Interest-Only Mortgage Calculator, enter your amount, rate, IO period, and full term, and find out today what your payment looks like in year eleven — before the bank tells you.
Related Tools You Might Like:
- Mortgage Calculator — standard principal-and-interest payments for any loan scenario.
- Loan Comparison Calculator — put multiple loan offers side by side and see which truly costs less.
- Compound Interest Calculator — model how voluntary principal payments and savings grow over time.
Happy planning!
Frequently Asked Questions
Q: What is a payment step-up on an interest-only mortgage? A: It is the jump in your monthly payment when the interest-only period ends. With no principal repaid during IO, the full balance is amortized over the shorter remaining term, producing a payment higher than both the IO payment and a standard loan's from day one.
Q: Does the Interest-Only Mortgage Calculator store my financial data? A: No. It runs entirely client-side in your browser; your inputs never leave your device and no sign-up is required.
Q: Can I use the calculator for an investment property or a bridge loan? A: Yes. Enter the amount, rate, IO period, and full term; the tool computes the phase payments, totals, and comparison the same way for owner-occupied, rental, or bridging scenarios.
Q: Is an interest-only mortgage ever cheaper than a standard loan? A: Almost never in total interest. Your balance stays at the full amount for longer, so you pay interest on more money for more time. The calculator quantifies the exact premium — IO is justified by cash-flow flexibility, not a lower total cost.